AI portfolio monitoring: how PE-backed companies run on their own data
The best portfolio monitoring starts inside the company. When each portfolio company runs on its own connected data, its managers get a reliable read every week, and the sponsor sees variance against plan without asking for it.
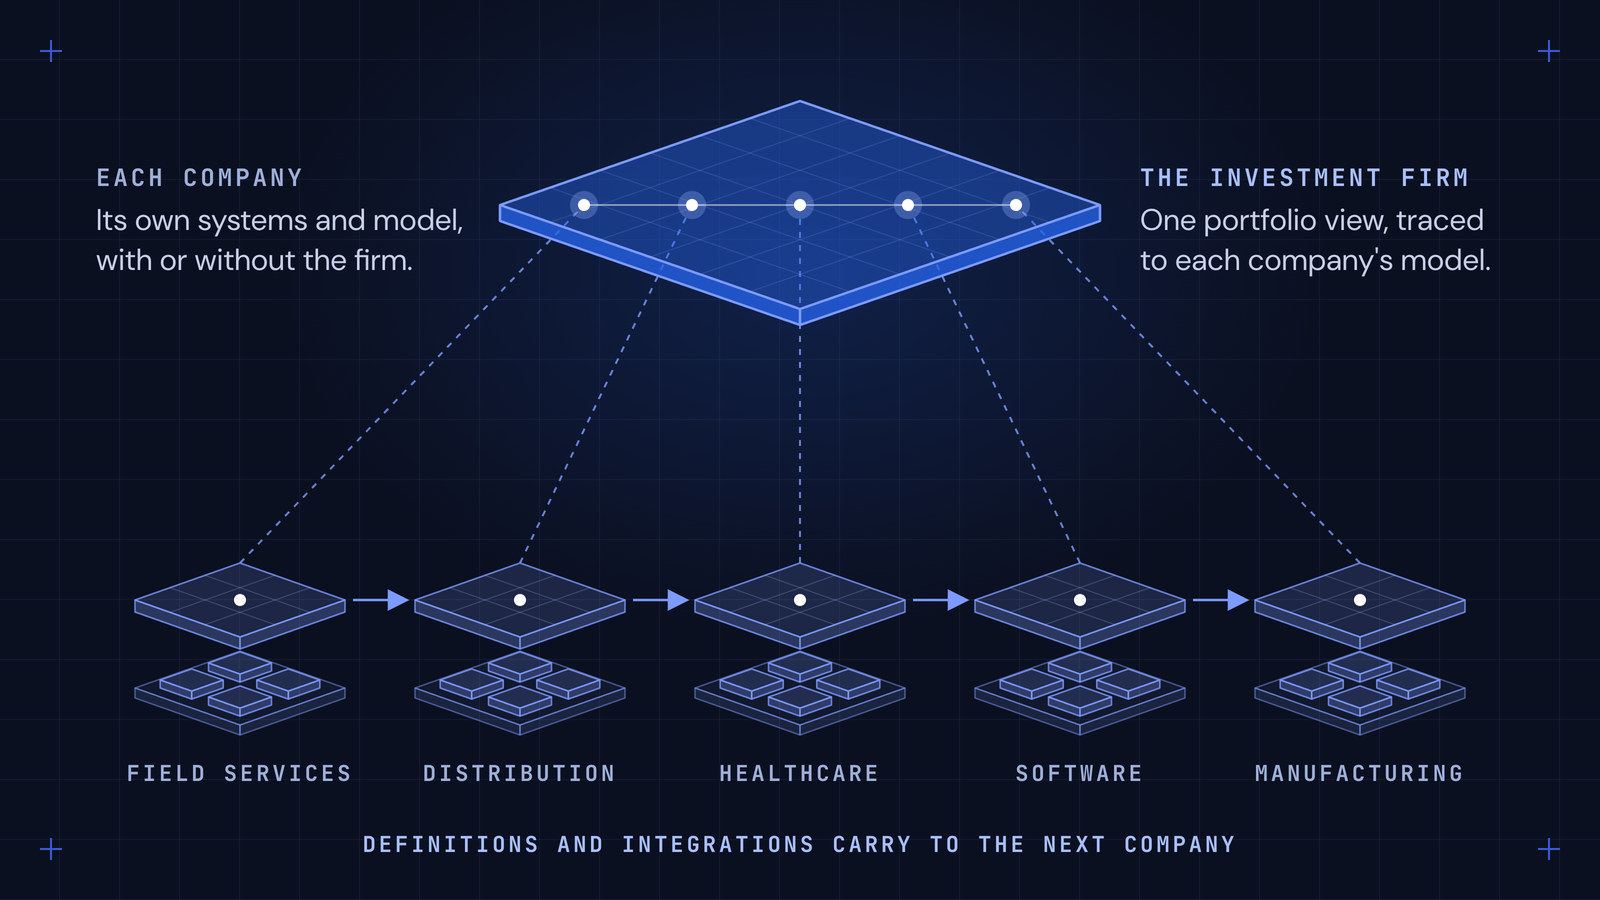
AI portfolio monitoring works best when it starts inside the portfolio company. Each company’s systems (the ERP, billing, the CRM, payroll, and the field operations or production tools) are connected and brought into one model of that business. The operating team gets a reliable read on its own numbers every week and acts on it. The sponsor’s monitoring then comes off the same model as a by-product: KPIs defined once, actuals checked against the underwrite as they land, variance flagged before anyone drafts the board pack.
That changes who monitoring is for. The usual version is built for the fund. Each company closes the month, rebuilds its numbers in the sponsor’s template and sends them up, and the fund learns about a problem weeks after it started. The version in this guide is built for the people running the company, and the fund gets a better view because the company has one.
This guide covers how that works, what each side gets, how it compares with portfolio monitoring software such as Chronograph, Cobalt and Allvue, and where people still have to make the call. It sits in our finance series; AI for investment firms covers the rest of the investment lifecycle.
What is AI portfolio monitoring?
AI portfolio monitoring uses connected data and AI agents to track how each company in a portfolio is performing against plan, continuously, from the company’s own systems. It replaces three manual jobs: collecting KPIs from each company, reconciling them against the plan the deal was underwritten on, and working out what has moved.
The older approach treats monitoring as a reporting problem. Get fifteen companies to send numbers in the same format on the same date, then put them in a dashboard. That solves consistency. It leaves the lag in place, because the numbers are only as current as the last pack someone assembled, and the company gets little out of it beyond a few lost days each month.
The newer approach treats monitoring as something a well-run company produces anyway. If a portfolio company already has its data connected and its metrics defined in one place, reporting to the sponsor is a view of something that exists. It updates when the business does.
Why does fund-side monitoring keep running late?
Because the work sits in the wrong place. Monitoring is usually designed from the fund’s side, but the effort falls on the portfolio company’s finance team. A typical mid-market company closes the month, then spends days on the board pack: pulling numbers out of the ERP, reformatting them into the sponsor’s template, chasing department heads for commentary, and checking the KPI definitions still match what the fund asked for last quarter.
Three problems follow from that. The numbers arrive late, since the pack is built after close. They arrive inconsistent, because each company defines gross margin or net revenue retention slightly differently until someone forces the issue (doing that by hand across a portfolio is a part-time job). And the company’s own managers are working from the same stale spreadsheets, so a regional manager in a field services business or a plant manager in a manufacturer learns about a margin problem at roughly the same time as the sponsor.
A dashboard on top of that process makes the late numbers easier to read. They are still late.
Dashboards show you last quarter. A company that runs on its own data knows what changed this week, and so does its sponsor.
What changes when the portfolio company runs on its own data?
The company gets the system first. We work in four steps, and the order matters.
Connect. Plug into the systems the company already runs: accounting or ERP, billing, CRM, payroll and HR, and the tools specific to the business. That might be a dispatch system in field services, a manufacturing execution system on the plant floor, warehouse management in distribution or product analytics in SaaS. Nobody has to replace anything.
Centralize. Bring those sources into one model of the business, a company ontology. It defines what a customer, a job, an order, a contract or a crew is, how they relate, and which system holds the truth for each fact. This is where KPI definitions get settled. Gross margin becomes one calculation, traced to source, used by the CFO and the sponsor alike.
Implement. Build the agents and apps the operating team uses on top of that model, with forward-deployed engineers embedded until they run in production. A weekly operations review written before Monday’s meeting. A margin view by branch or product line. A contract check that compares what each customer is billed with what their agreement says.
Decide. Managers act on what they see that week. Every part of this exists to get a better decision on pricing, staffing, collections or inventory while it can still change the month.
Sponsor monitoring falls out of the second step. Once the company’s numbers live in one model with agreed definitions, the fund’s view is a set of KPIs read from that model on a schedule and compared with the underwrite. Nobody has to run a separate reporting project.
How does AI portfolio monitoring work, step by step?
- Connect the source systems. Each portfolio company’s finance and operating data feeds its model through integrations, continuously or on a schedule tied to close. Nobody uploads spreadsheets.
- Define the KPIs once. The sponsor and the company agree the metrics and how each is calculated. The model then calculates them the same way every period, and every figure can be traced to the system it came from.
- Load the plan. The budget, the value creation plan and the assumptions the investment committee underwrote (the EBITDA bridge, the retention assumption, the pricing plan) are stored as structured records, so actuals can be checked against them line by line.
- Watch for variance. Agents compare new actuals with plan as they land and flag anything outside the agreed tolerance, tagged to the line item and the assumption it breaks.
- Route the exception. A flag goes first to whoever can act on it, usually inside the company: the regional manager, the controller, the CFO. The deal lead and operating partner see the same flag with the context attached.
- Draft the pack. At month end, an agent assembles the board and sponsor reporting from the reconciled model. The CFO reviews it and adds commentary.
The assumptions worth watching after close are often the ones tested in diligence. If the thesis relied on customer concentration falling or churn improving, those should already exist as structured records from diligence and the investment memo. Monitoring keeps checking them against what actually happens.
What does the operating team get each week?
Most portfolio monitoring software skips this part, and it is the reason company leadership backs the work instead of tolerating it. The examples below show what the model connects and what managers see, by industry.
| Industry | What the model connects | What the team sees each week |
|---|---|---|
| Field services | Dispatch, billing, payroll, customer contracts | Margin by crew and region, jobs billed off-contract, overtime running above plan |
| Manufacturing | ERP, production systems, purchasing, quality records | Scrap and yield by line, material cost against standard, late orders by customer |
| Distribution | ERP, warehouse management, pricing, CRM | Gross margin by customer and SKU, price overrides, slow-moving inventory |
| SaaS | Billing, CRM, product usage, support | Net revenue retention by cohort, accounts with falling usage ahead of renewal, pipeline coverage |
A PE-backed field services company we work with shows what this looks like in practice. We connected its data warehouse, finance, billing, HR and every customer contract into one model, sized the value creation opportunity by area of the business, then built what the numbers pointed to. It now has a contract review app that found accounts where pricing had drifted from the agreement, a crew productivity view for operations, finance reporting that runs from the model, and an agent that writes the weekly operations review before Monday’s meeting. The sponsor’s view of the business reads from the same model its managers use.
A PE-backed, multi-region services business shows the predictive end. Its margin and billing problems used to surface in the monthly review, weeks after close, by which point some had become customer disputes. With its operating, billing and accounting systems reconciled into one foundation and predictive models on top, problems now surface early enough to fix. The result was 30% fewer quality and billing incidents, and five times as many high-risk jobs caught as random audits had found.
What does the sponsor see?
Variance against the plan that matters, early, without having to ask for it.
Actuals against the underwrite. Most monitoring compares this quarter with last quarter. The more useful comparison is actual performance against what the investment committee approved at close. Because the plan is stored in the model, each new actual is checked against the number the deal was priced on.
One definition across the portfolio. Each company keeps its own systems, but the KPIs the sponsor tracks are defined the same way in every company’s model. For a B2B SaaS growth fund, we built a pipeline that takes founder financials in any format, consolidates each company into one structured record, and calculates ARR, net revenue retention, burn and runway the same way every period, with each figure traced to the document it came from (case study).
Less time assembling. Pluris independently published a case study on one DealSage deployment at a mid-market PE firm. Monthly portfolio P&Ls that arrived in every format are now reconciled into one standard automatically, which gave the team back about 40 hours a month, and the system was live in under four weeks (Pluris case study).
Earlier conversations. When a flag reaches the operating partner in the same week the company’s managers see it, the call with the CEO is about a decision that is still open. The board meeting stops being where bad news is first heard.
How does this compare with portfolio monitoring software?
The incumbents are good at what they were built for, so it helps to be precise about which job each one does.
| Option | Built for | Where it fits |
|---|---|---|
| Chronograph | LP reporting and standardized portfolio data collection | The fund’s reporting layer for its investors |
| Cobalt (Cobalt LP) | Portfolio monitoring and LP reporting across a fund | Consistent quarterly packs and fund-level analytics |
| Allvue | Fund administration plus operational workflow | Funds that want administration and monitoring from one vendor |
| Carta | Cap tables and equity management | Ownership data, especially in venture and growth |
| A company ontology with embedded engineers | Each portfolio company’s own connected data, agents and apps | Weekly operating decisions inside the company, with sponsor variance read from the same model |
Chronograph and Cobalt solve a hard problem: getting many companies to report in the same format on the same schedule, so a fund can produce a consistent pack for its LPs. Both start from numbers once they have been collected. Neither was designed to connect a company’s dispatch or production systems, or to give its managers a weekly view they run the business on.
In practice the two coexist. A fund can keep Chronograph or Cobalt for LP reporting and feed it a cleaner, pre-reconciled dataset from each company’s model. The LP report improves too, since it is built from numbers that were reconciled at source.
So there is no single best private equity portfolio management software. The category covers jobs that barely overlap, and the sensible choice depends on which one is costing you most.
How do you roll it out across a portfolio?
One company at a time, starting with a decision.
Pick a portfolio company with a clear value creation lever and numbers nobody fully trusts. That could be pricing leakage in a distributor, crew utilization in a field services business, scrap in a manufacturer or churn in a SaaS company. Put a figure on what getting that decision right is worth. Then connect the systems that feed it, build the model, and put the first workflow in front of the people who make the decision. The sponsor’s KPI feed for that company comes from the same model, so it arrives with the first workflow.
The second company goes faster. Integrations for the accounting packages and CRMs that mid-market companies tend to run carry over, as do the KPI definitions and much of the model’s structure. Each company keeps the parts specific to its business. Over time the sponsor has a portfolio where every company runs on its own model and reports from it, and the portfolio view is a roll-up of reconciled data.
Two practical points. Company leadership has to own the work, because the value starts with their decisions, and nobody keeps feeding a system that exists only for the fund. And connected, defined, traceable data is useful well beyond monitoring: it makes the next acquisition easier to integrate and gives a buyer at exit far less to reconstruct.
Where does AI still need a person in portfolio monitoring?
Wherever judgment lives, which is most of it. A model can tell you gross margin slipped 300 basis points against plan. It cannot tell you whether that is a pricing problem, a mix shift or a one-off cost that reverses next month, and it should not decide what the board hears about it.
Inside the company, the controller still checks the close and the regional manager still decides whether to move crews. At the fund, the operating partner still calls the CEO, and the deal lead still decides whether a flag is noise or an early warning. What the agents remove is the lag between a number moving and the right person knowing, along with the manual work of assembling the evidence. That is a lot of value, and the decision still belongs to a person. Our post on which finance work AI should do and which people should keep walks through that split in a month-end close.
Trust depends on traceability. Every figure in the weekly review or the sponsor pack should lead back to the system and record it came from. If people cannot check a number, they rebuild it in a spreadsheet, and the lag comes straight back.
How DealSage does portfolio monitoring
DealSage connects each portfolio company’s systems, brings them into one model of the business on our platform, and builds the agents and apps its team uses, with engineers embedded until they run in production. The sponsor’s monitoring reads from those same models. We were built by alumni of J.P. Morgan and Palantir, and we are not affiliated with Palantir. Our guide to Palantir alternatives for mid-market companies explains how the approach compares.
We started with private equity firms, and sponsors still introduce us to many of the companies we work with. The work itself happens inside the company, aimed at the decisions its managers make every week.
If you run a PE-backed company, or a portfolio of them, and the monthly numbers arrive too late to change anything, talk to us. We start with one company and one decision.
Frequently asked questions
- How can AI help with portfolio monitoring for PE firms?
- AI automates the slow, manual parts of monitoring: collecting KPIs from each portfolio company, reconciling actuals against the plan the deal was underwritten on, and spotting what has moved. It works best when each company's own systems are connected into one model of the business, so the numbers are defined once, traceable to source and current. The sponsor then sees variance as soon as it shows up in the actuals, and the company's managers see it at the same time, while there is still room to act. People still interpret the variance and decide what to do.
- What AI tools help portfolio companies track KPIs for their PE owners?
- The useful tools connect directly to the systems the company already runs, such as the ERP or accounting package, billing, CRM, payroll and operating tools like dispatch or warehouse management, and calculate the agreed KPIs automatically. That saves the finance team from rebuilding a reporting pack every month. The bigger gain comes when the same connected data also gives the company's own managers a weekly view of margin, utilization or retention, because then the reporting to the sponsor is a view of something the business already uses.
- What's the best private equity portfolio management software?
- It depends on the job. Chronograph and Cobalt are strong at LP reporting and standardizing data collection across a portfolio. Allvue adds fund administration and operational workflow. Carta is the default for cap tables and equity management. None of them was built to connect a portfolio company's operating systems, give its managers a weekly view they run the business on, and check actuals against the specific assumptions in the underwrite. A company-level model with embedded engineers does that, and it works alongside the fund's reporting software.
- How do PE firms automate portfolio reporting?
- By connecting each portfolio company's finance and operating systems to a structured model of that business, defining the KPIs once, and reading them on a schedule tied to month-end close. The sponsor sets the KPI definitions and cadence with each company. An agent drafts the board and sponsor pack from the reconciled data, and the CFO reviews and adds commentary. The result is a portfolio view that updates itself, with every company's numbers defined the same way and traceable to source.
- Does AI replace portfolio monitoring dashboards?
- No. A dashboard is a good place to look at a trend once the numbers exist. AI changes how the numbers get there and how soon people learn they have moved. Agents read actuals as they land, compare them with plan and send a flag to the person who can act on it, often before anyone has opened the dashboard that week. Keep the dashboard for the trend. Just do not let it be where you first learn about the problem.
- What is the difference between LP reporting software and portfolio monitoring?
- LP reporting software standardizes what a fund sends its limited partners: capital account statements, fund performance and portfolio company summaries in a consistent template. Portfolio monitoring is the earlier, internal job of tracking how each company is performing against plan, which later gets summarized for LPs. A fund can have excellent LP reporting and still monitor its portfolio on a lag of several weeks, because the reporting software only formats what has already been collected.
- Where does AI still need a person in portfolio monitoring?
- Wherever the interpretation happens. AI can tell you a company's gross margin slipped 300 basis points against plan. It cannot tell you whether that is a pricing problem, a mix shift or a one-off cost that reverses next month, and it should not decide what the board hears about it. Inside the company, managers still decide whether to change pricing or staffing. At the fund, the operating partner still calls the CEO and the deal lead still judges whether a flag is noise or an early warning.
See it on your own deals.
We build AI on your firm's own record, then embed it in the workflow your team already runs. Start with one process.